Vol.234 宏观漫谈110|全球流动性的困境与中国五类经济主体的金融结构转型(9.2录制)
全球流动性或已见顶,AI数据中心与美债、美股争夺资金,资本开支转向惩罚激进;李丰的英伟达实验提示延期、涨价、自由现金流下降和应收高企风险。中国融资结构与房地产、保险、A股筹码调整或重塑居民资产配置,滞胀与泡沫出清仍待观察。
Vol.229 宏观漫谈109|我们正处于一个美元主导的资本周期上升阶段尾部(8.6录制)
美元计价资产正处于资本周期上升阶段尾部,增量资金不足使市场转向宽幅轮动与存量博弈。美国美债将突破40万亿美元,利息与国防开支合计接近3万亿美元、占财政收入一半以上,加息和降息都受约束。日元流动性反转、数据中心私募债与霍尔木兹海峡构成黑天鹅,后续需观察美债发行压力、黄金及中国超额储蓄是否转化为持续流入。
Scott Bessent: Fixing the Fed, Tariffs for National Security, Solving Affordability in 2026
Bessent’s 2026 thesis pairs roughly 6% nominal growth with a $200-$300 billion fiscal contraction, targeting mid-five deficit-to-GDP.He frames tariffs up to 145% as national-security leverage, not permanent revenue, with fentanyl rates later halved to 10%.Execution risk centers on whether Fed normalization, $1,000-$2,000 refunds, and capex incentives can repair affordability.
The Fairfax Way with David Thomas $FFH.TO
Fairfax delivered a 19.2% cumulative annual return from 1985 through 2024 as insurance, investments, and non-insurance operations evolved into three concurrent earnings engines after costly lessons in under-reserving and hedging.Buybacks have retired more than 20% of shares but recently slowed; succession and the 15% long-term book-value-growth objective now test whether this second wind can outlast Fairfax’s “seven lean years, seven fat years” rhythm.
Vol.193 宏观漫谈96|十月中国经济数据观察(11.20录制)
十月数据呈现PMI偏弱、价格略超预期与社零受长假和补贴支撑的混合信号,居民短贷骤降更可能包含助贷监管带来的供给收缩。年化24%利率上限可能令全年助贷缩量至少1万亿元、甚至1万亿—2万亿元,相关平台四季度业绩承压;与此同时直接融资已接近社融半壁江山,AI数据中心债务则需由真实现金流验证。
市场概述2025年10月28日
主讲人判断AI泡沫虽存在,但当前ROE、盈利路径和已释放的波动率使近期尾部暴跌概率不大,年内大概率仍降息两次。政府关门造成的长债供给错位或带来十年期利率交易机会,但汽车信贷违约与传统车企利润下滑构成更集中的产业链重估风险。
The Data on America's Economic Split | Andrew Milgram Interview
Patrick O'ShaughnessyAndrew Milgram
Anonymized data from 1,200 US middle-market companies shows EBITDA down 20–25% since 2019, negative net profits for two years, and another 20% failing debt-service coverage in 2024.Tariffs above 5–6% could crush these firms, while private-credit defaults may be understated; waiver rates, amendment rates, and PIK exposure are more revealing than reported defaults.
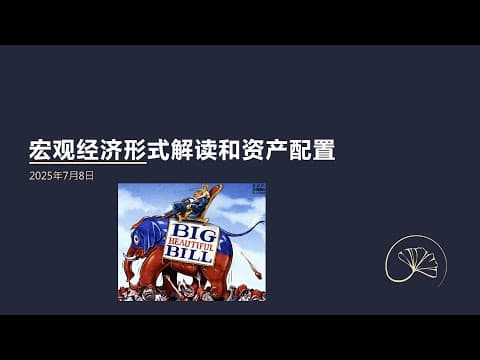
市场概述2025年7月8日
BBB与关税对明年经济的负面影响或仅约0.25%,真正的资产周期变量在减税、持续支出与去监管。未来三至六个月美债可能因TGA由4,800亿补至8,500亿美元及eSLR延后松绑而承压,但银行养券买盘仍可能接力。147K非农掩盖私营招聘放缓,七月不降息、九月观察;指数估值偏高之际,AI与半导体的供需缺口或成为十年级别主线。
Vol.168 宏观漫谈84|变局中的中国经济:一季度数据、贸易战、人口结构和内需(4.23录制)
一季度GDP增长5.4%由投资和约40%的出口贡献托住,社零增长4.6%却低于预期,关税落地后内需能否承接转内销货值成为关键变量。若约1000亿美元出口转内销,终端需求可能对应约1.5万亿元人民币并要求社零增速升至约7%—9%,同时需观察90天窗口、中美deal与香港离岸融资中心的演变。
March 2025 Fintwit Book Club: Diary of a Very Bad Year with Byne Hobart from The Diff
Expertise offered a probabilistic edge, not immunity from error, as the manager’s March 2008 calls show.Systemic crisis emerged when uncertainty over AAA collateral seized financial plumbing, while cheap funding scaled tiny credit-pricing errors into concentrated books.Hobart says AI economics do not support capex, though shorter asset duration may limit losses; peak spending could be depreciated by 2030 or 2031.